All Categories
Featured


Security Plans for Term Insurance
Table of Contents
As quickly as the very first premium is paid, the whole survivor benefit is set aside for your family. Earnings tax-free death benefit: The survivor benefit of a life insurance policy is not usually subject to federal income taxes. Tax-deferred growth: The growth of money worth within whole life insurance is tax-deferred while the funds remain in the policy.
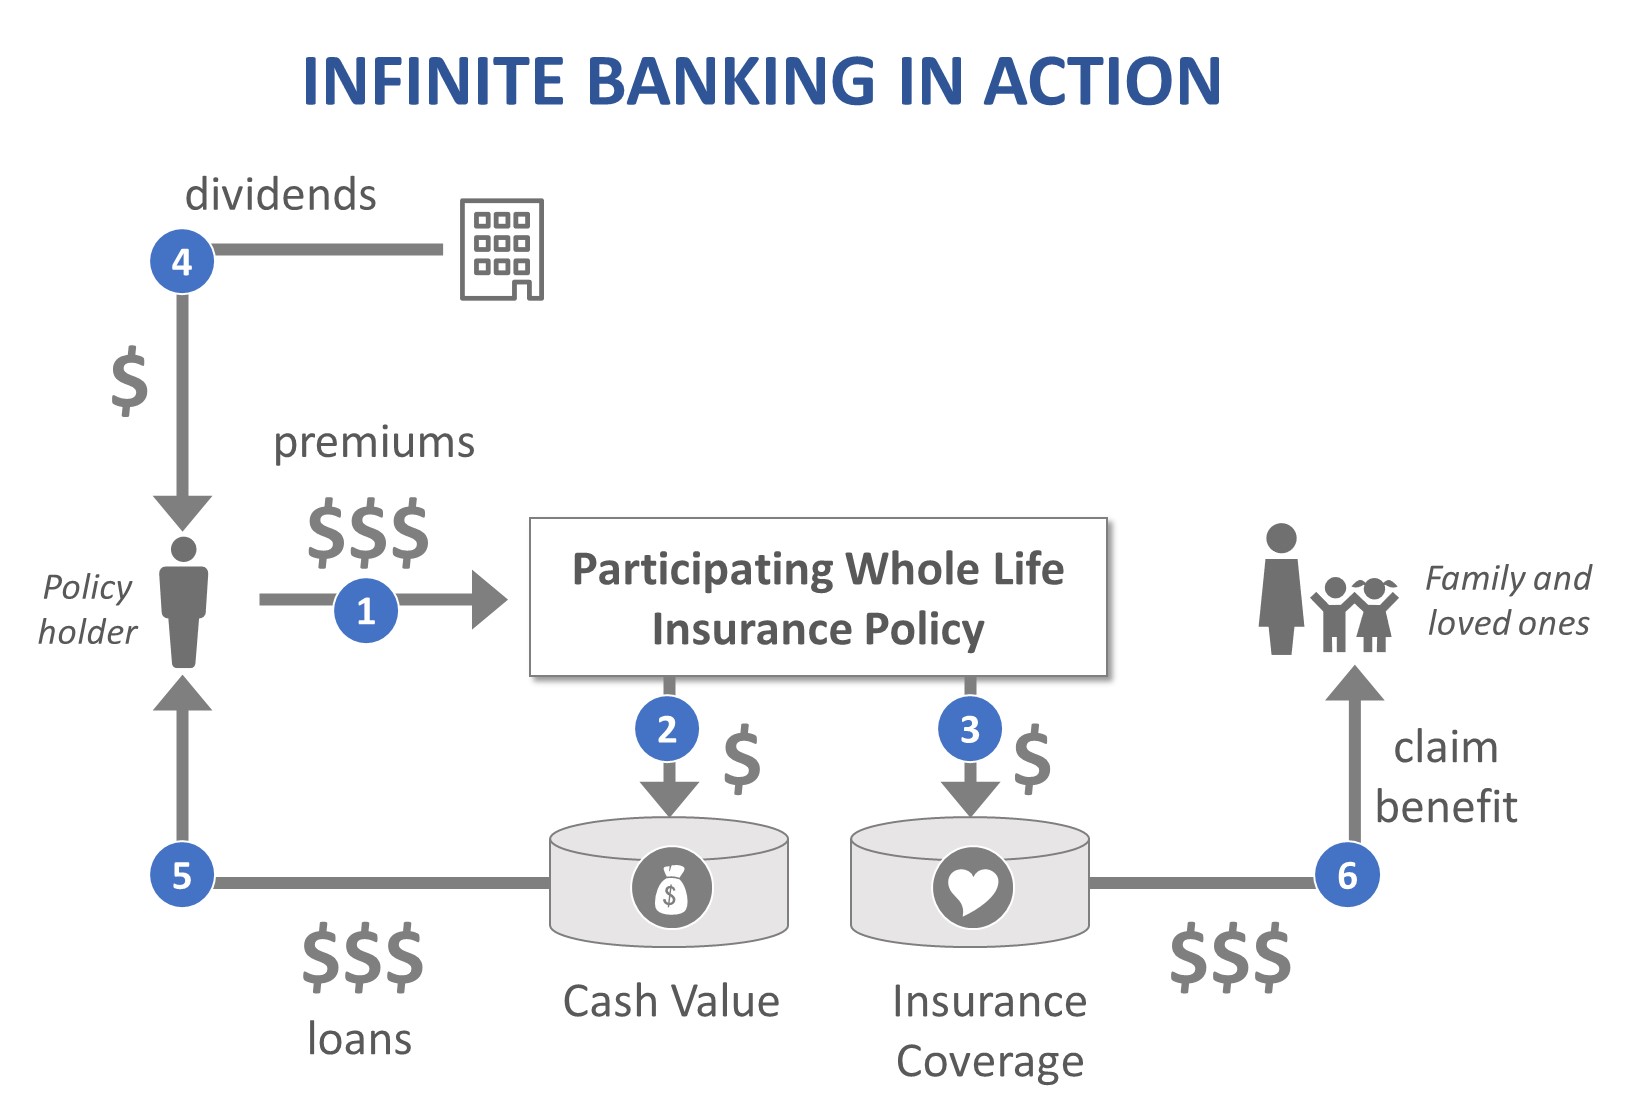
This suggests withdrawals to the degree of cost basis are thought about an earnings tax-free return of expense basis. Tax-favorable access to cash worth loans for any factor: During the insured's life, money worth loans taken against an entire life policy are not considered to be a taxable occasion, even though the policy might have a large gain in excess of premiums paid.
Self-funding: The policy can spend for itself with time by using dividends to pay premiums, which adds to the policy's savings part. Special needs protection: A whole life policy can continue to be funded even if you are disabled. When you elect the Waiver of Premium rider9, if you suffer a qualifying disability, your policy will continue to offer survivor benefit protection, have cash worth development, and pay dividends even while you aren't paying premiums.
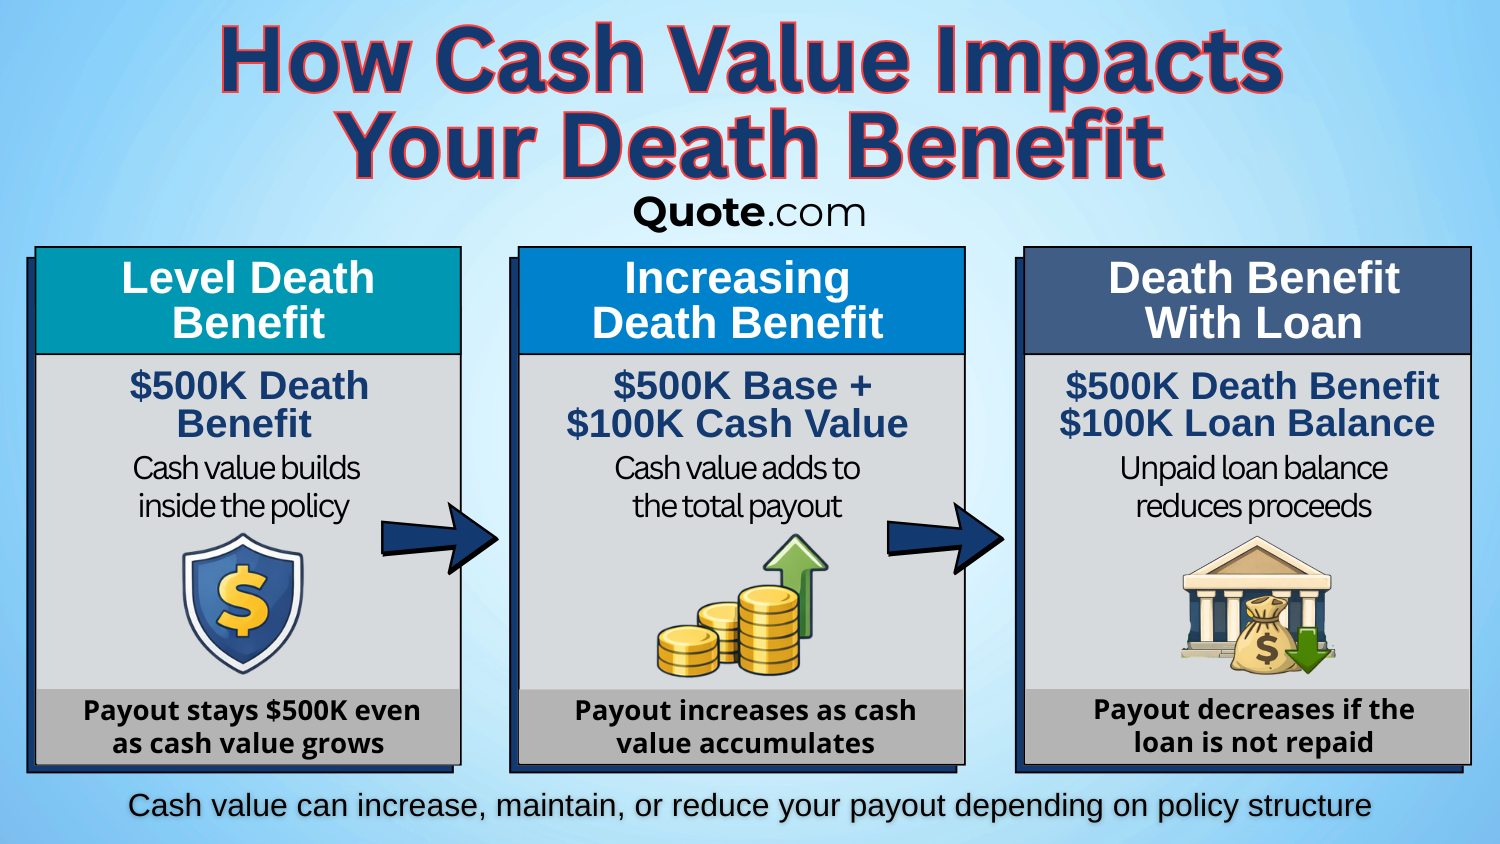
10Distribution: If appropriately performed, life insurance helps prevent probate and can provide beneficiaries with higher personal privacy than may be paid for by a will; a will ends up being public as soon as probated, whereas survivor benefit distributions are usually private, contractually driven deals. When a policy loan has been taken, the annual dividend can be utilized to help repay the policy loan.
Functions, provisions, and costs vary from one insurer to the next, and each whole life agreement is distinct to the insurance policy holder. Entire life insurance rates depend on factors such as age, health, and coverage amount, so it is very important to consider these when evaluating policies. Normally speaking, there are 2 basic kinds of payment structures for entire life: Level premium entire life: This is the most typical kind of entire life insurance.
Indexed Universal Life Options for Retirement
Restricted payment entire life: This kind of policy has a fixed level premium like a level premium whole life policy, however the premium is only payable for a set time period. The advantage is that they are guaranteed to be paid up at the end of the payment period, so no payment is needed at later ages.
Their accessibility and expense depends on the policy and the insurance company. In addition to the Waiver of Premium rider mentioned above, some other choices provided by Guardian consist of: Paid-Up Additions Rider: The PUA rider can help increase the accumulation of tax-deferred money values and death advantage. The greater the premium paid into the rider, the greater the protection afforded by the policy.
It gives you an unique chance for index-linked upside potential and the floor makes sure that your year-to-year downside market direct exposure is limited. Accidental Survivor Benefit: Supplies an extra death benefit if death takes place by unexpected bodily injury. Accelerated Benefit Rider: Offers sped up benefits, permitting you to access a portion of the survivor benefit early if you are identified with a persistent or terminal disease.
Exploring How Whole Life Insurance Operates
Surefire Insurability Alternative (GIO): Gives the policy owner the right to buy additional insurance without proof of insurability. The GIO can become even more valuable in case of special needs: An insured who is handicapped and has their premium waived may exercise the GIO rider, and Guardian will pay the premium on the new policy A whole life insurance policy is among the most crucial monetary purchases you can make.
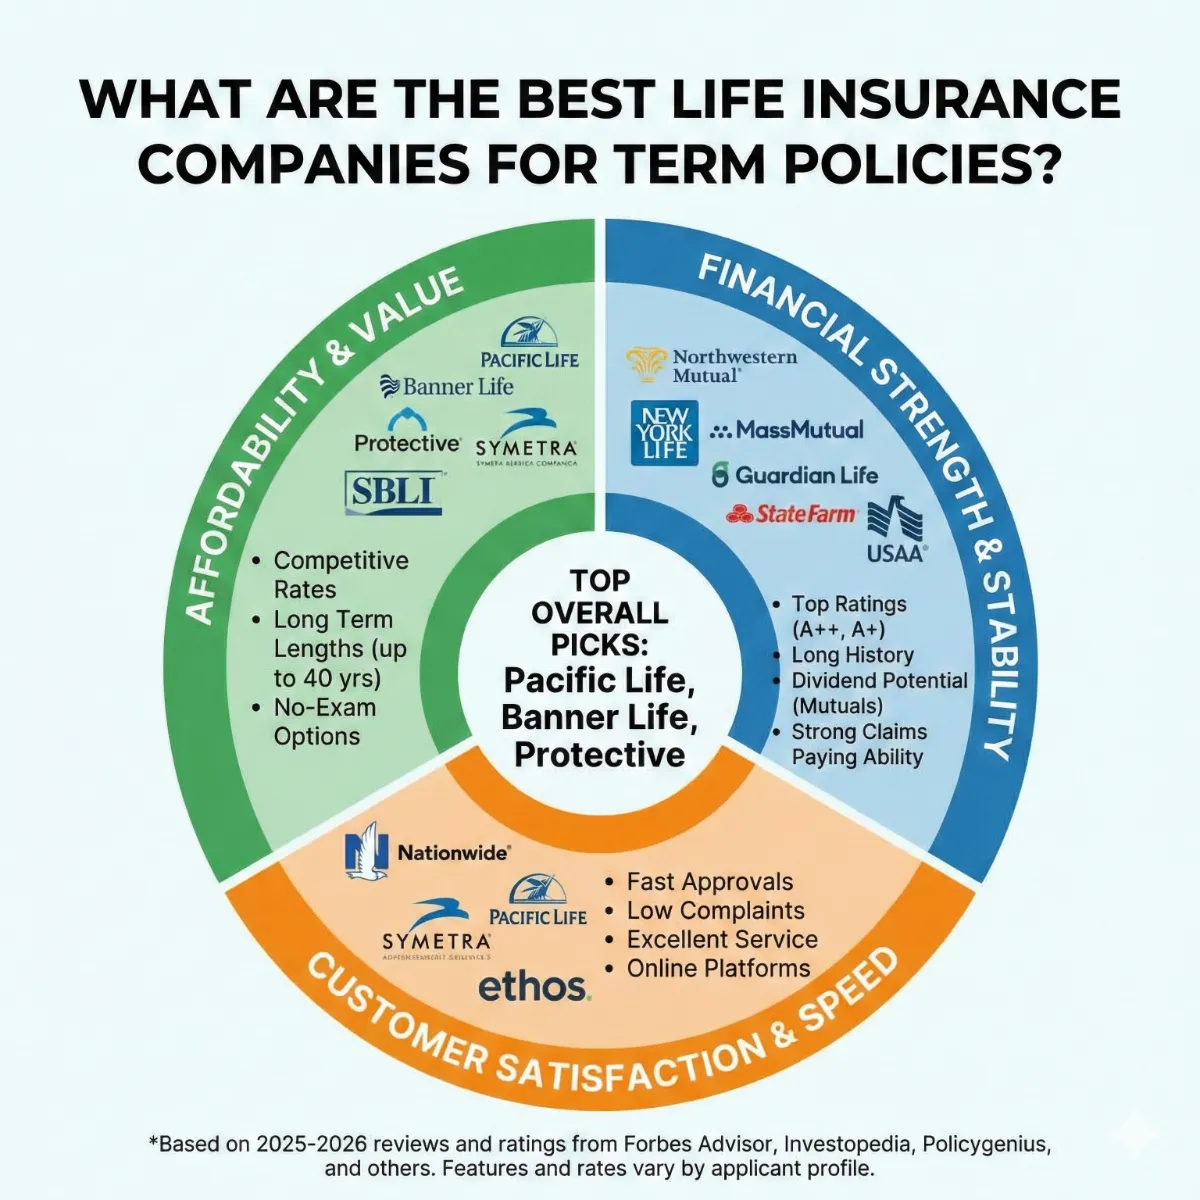
12 Comparing life insurance companies and their life insurance offerings such as whole life, universal life, repaired premiums, guaranteed death benefits, and cash worth growth is essential to discovering the ideal policy for your requirements.
Discuss your circumstance with an insurance professional or monetary expert who understands entire life insurance coverage and can guide you to the service that finest fulfills your requirements. If you do not know such a professional, ask a good friend or coworker for a suggestion.
An entire life policy has cash worth that grows in time. You can cash it out to assist supplement retirement, or borrow against it at any time, for any factor. Whole life policies have a part described as the policy's money worth: A part of your premium dollars can grow gradually on a tax-deferred basis, so you don't pay taxes on the gains.

Latest Posts
Security Plans for Term Insurance
Final Expense and Burial Insurance Options
Selecting the 2026 Medicare Advantage Coverage