All Categories
Featured

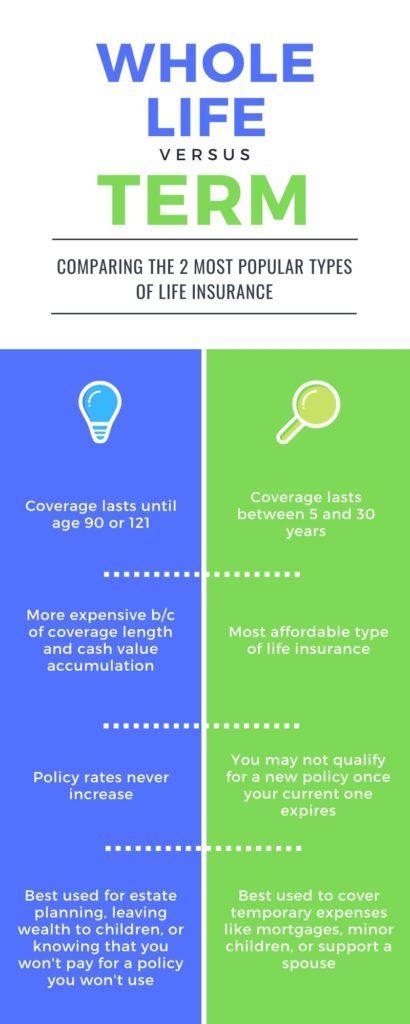
How Whole Life Insurance Works
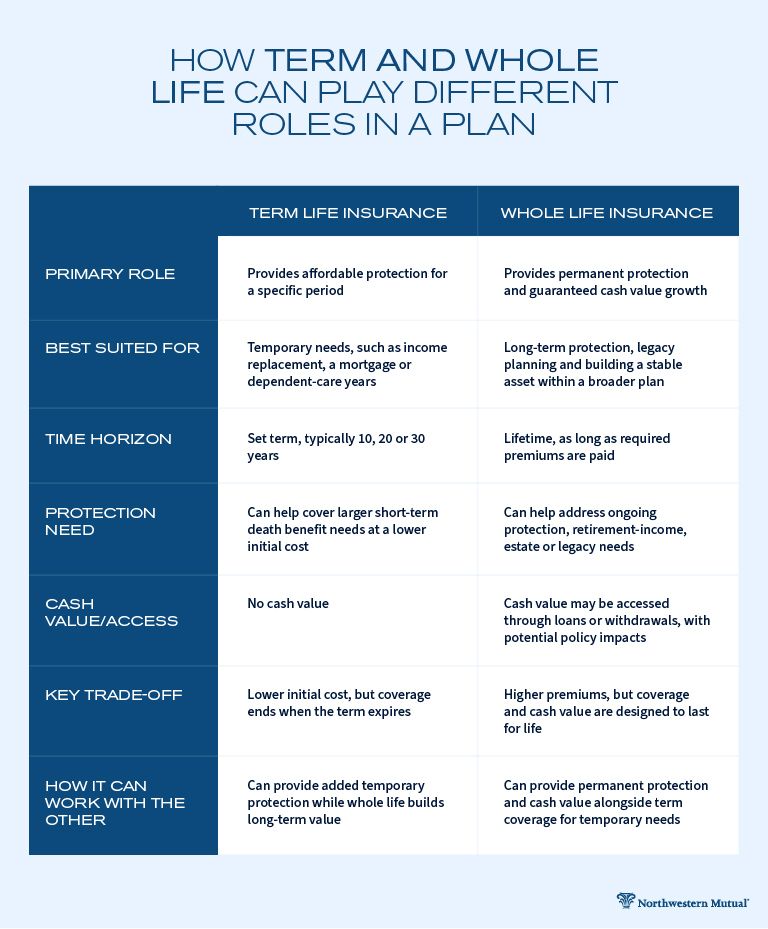
A whole life insurance policy in a very actual sense is more than simply life insurance coverage. It's a flexible financial instrument that assists protect families and organizations from unpredictability while helping them develop and improve wealth. If that is essential to you, this article can help answer crucial questions, including: Whole life insurance coverage is, most importantly, long-term life insurance security that lasts your whole life; by contrast, term life insurance coverage just covers you for a particular variety of years.
Medicare in EscondidoEntire life insurance coverage policies likewise have a "cash worth" element a life-long financial asset. 1 Since life insurance coverage protection is considered helpful to society, it has actually been given tax advantages you may not discover with many other financial instruments. 2Every whole life contract is distinct to the insured person, taking into consideration their death danger, desired protection level, and optional functions (for instance, a cost-of-living change rider).3 When you get a whole life policy, there's an underwriting procedure in which you may undergo a medical test.
Then, based on your life span, the insurance company's actuaries set 4 guaranteed values4: A guaranteed level premium: Whole life insurance policies have actually fixed premiums that are guaranteed never to alter. As long as you keep making premium payments, the policy will stay in impact, and each premium payment contributes to the policy's cash value.
A surefire cash worth: A money worth that is guaranteed to grow at a set rate each year until it amounts to the face amount of the policy at a specified age, typically age 100 or 121. An ensured endowment: The survivor benefit is ensured to be paid if the insured is still living at the age specified in the contract, normally age 100 or 121. A portion of each premium payment is designated to a money value account, which grows over time.
While there's no guarantee that dividends will be stated each year, Guardian has actually paid them every year since 1868, even during wars, pandemics, or stock exchange turbulence. Depending upon your requirements, you can choose to use your dividends in various ways. One option is to acquire paid-up additions (PUAs).7 A PUA is guaranteed permanent, paid-up life insurance.
Strategic Security Plans for Whole Life Coverage
Gradually, the compounding build-up of PUAs can help to balance out the impacts of inflation by providing a higher survivor benefit and cash value. Dividend build-ups can also be withdrawn income tax-free, up to the policy basis (i.e., the amount of premiums paid to date). In addition to purchasing PUAs, Guardian offers insurance policy holders these dividend choices: Get in cashReduce premiumPurchase extra term insuranceAccumulate with interestApply to exceptional policy loansHere's how the insurance survivor benefit of an entire life policy can grow with paid-up additional insurance bought by dividends.
It can also offer several other financial advantages. The majority of people see the significance of guaranteeing the value of home, such as their home or automobile, so they buy casualty insurance. The human life value8 of an individual among the most valuable possessions of a family or business is also insurable.
The death benefit of life insurance can help guarantee the financial continuity of a family when it is faced with the death of a loved one, by helping provide funds that can be used for: Payment of a mortgageEducation fundingIncome needsTime far from work to take care of household needsFuneral costs Arrearages Services looking to develop a service continuity strategy in the event of the death of a partner or essential staff member have special insurance coverage needs.
Life insurance can help deal with four major areas of business techniques: The funding of buy-sell arrangements and stock redemption plansThe financing of supplemental retirement programsKey person indemnificationPayment of loans and home loans Preparation for the organized transfer of property at death can help to reduce taxes and offer heirs in such a way that shows your desires.
It can allow the policy owner to utilize estate possessions in ways that might not be possible otherwise. For example, it can be the "approval slip" that lets you utilize other elements of your retirement income and individual net worth. It can give you the power to spend possessions that may not otherwise be utilized.

Latest Posts
Accessing Final Expense Options for Veterans
Building Long-Term Security with Whole Life Insurance
How Whole Life Insurance Works